Mortgage Broker in Thornhill, Ontario 2026: What You Actually Need
 By Jenny Tate
Thornhill has a renewal problem most of its homeowners do not know they have. It is one of the GTA's most established communities, which means a large share of its residents have owned the same home for 10, 15, or 20-plus years and renewed with the same lender every term out of habit. That loyalty is the single most expensive financial decision many Thornhill homeowners make, and it repeats every five years. Expert advice at the right moment changes the math.
If you are buying, renewing, or refinancing in Thornhill in 2026, the question that actually matters is not "which bank" but "which lender for this file." That is what an independent mortgage agent in Thornhill does: route your specific situation, whether it is a renewal on a long-held detached, a move-up purchase, or an incorporated-professional file, to the lender most likely to fund it on the best terms, from a panel of 50-plus banks, credit unions, monolines, and alternative lenders. Pair this guide with our renewal versus refinance decision guide.
Short answer
An expert mortgage agent in Thornhill, Ontario specializes in renewals for long-term homeowners (10-20-plus years), incorporated professionals, and equity access on substantially appreciated homes. You may qualify for a rate lower than the one quoted in your renewal letter; on a $900,000 balance, each 0.10% of rate is about $900 of interest in the first year. Thornhill straddles Vaughan and Markham, neither of which charges a municipal land transfer tax, a $14,000-$20,000 closing-cost saving versus an equivalent Toronto purchase.
Thornhill 2026 market: the Vaughan and Markham split
Thornhill sits at an administrative crossroads. The western half, centred on Yonge Street and Bathurst, falls within York Region (City of Vaughan). The eastern section sits within Markham. This creates quirks in municipal services and address conventions, but for mortgage purposes both halves share one useful advantage: neither Vaughan nor Markham levies a municipal land transfer tax, so a Thornhill purchase saves roughly $14,000 to $20,000 in closing costs compared with an equivalent Toronto property. The provincial Ontario land transfer tax still applies.
Per Toronto Regional Real Estate Board (TRREB) data through early 2026, Thornhill price ranges look roughly like this:
- Detached homes in established pockets: $1.5M to $2.6M, with renovated homes on premium lots above that.
- Townhomes and semis: $950K to $1.4M.
- Condos along the Yonge corridor and near Highway 7: $620K to $900K.
The defining feature of the Thornhill market is stability. Detached homes here change hands less often than in newer suburbs, which means a large proportion of current owners hold properties that have appreciated substantially since purchase. That appreciation creates two financing realities: very large renewal balances, and very large amounts of accessible home equity.
Mortgage broker vs mortgage agent in Thornhill: what is the difference?
When most Thornhill residents search "mortgage broker" they mean any licensed, independent mortgage professional who shops their file across multiple lenders. In Ontario, the FSRA uses two licence titles, and the distinction matters less than you might think.
| Title | What they can do | Works at | Cost to borrower |
|---|---|---|---|
| Mortgage Agent Level 1 | May deal with financial institutions and lenders approved under the National Housing Act. | A licensed brokerage (e.g., Tango Financial Mortgage (ON) Corporation, FSRA #13691) | Zero for standard residential (lender pays) |
| Mortgage Broker | May deal with all mortgage lenders, including private lenders, and may supervise agents at a brokerage | A licensed brokerage | Zero for standard residential (lender pays) |
| Bank specialist | One bank's products only. Cannot shop across lenders. | The bank's branch or contact centre | Zero, but the cost is in the rate |
Jenny Tate is a Mortgage Agent Level 1 (FSRA #M22002086) operating under Tango Financial Mortgage (ON) Corporation (FSRA #13691). In Thornhill searches, "mortgage broker Thornhill" and "mortgage agent Thornhill" are often used for the same independent professional model, but the licence class still determines which lender types the professional may deal with.
The one distinction worth knowing: if you are working with a private lender on a short-term or bruised-credit file, the assessment and transaction must be handled by a Mortgage Agent Level 2 or Mortgage Broker. A Mortgage Agent Level 1 is not authorized to handle private mortgages.
Thornhill mortgage rates 2026: what you are actually looking at
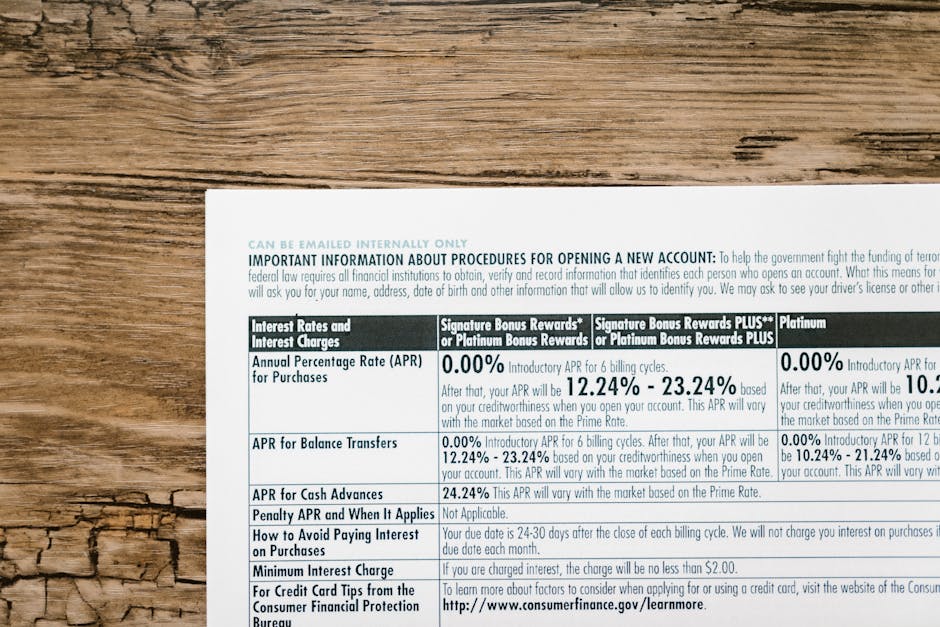
Thornhill's pricing creates a rate reality most residents do not expect. Purchases at $1.5M or more, or with 20% or more down, are generally uninsured (CMHC and Sagen insurance requires a purchase price under $1.5M). The uninsured rate tier is typically 0.10% to 0.20% higher than the insured tier.
In May 2026, approximate ranges for Thornhill files:
- 5-year fixed, insured (under $1.5M with less than 20% down): high 4% range at leading monoline lenders (First National, MCAP, CMLS)
- 5-year fixed, uninsured (20% or more down, or $1.5M and over): low to mid 5% range at monoline lenders; Big-Five banks often 0.20%-0.40% above that on first offer
- Variable rate, uninsured: prime minus 0.40% to 0.60% (prime is currently 4.45%), so roughly 3.85% to 4.05%
- Renewal, straight switch: same rate tier as uninsured purchase; stress test does not apply at maturity as long as balance and amortization stay the same
The Thornhill price point means most homeowners at renewal are dealing with balances in the $700,000 to $1.4M range. A 0.30% rate difference on a $1,000,000 Thornhill mortgage is about $3,000 of interest in the first year, and less in later years as the balance is paid down. That is why comparing written offers at renewal, rather than auto-signing the bank's mailed offer, is worth the time.
The framework: what Thornhill buyers and owners actually need
Run YOUR numbers
Model your Thornhill mortgage payment using current 2026 rates.
Open the free mortgage calculatorThornhill files fall into four broad groups, each with complexity the Big-Five branches handle awkwardly.
- Long-term homeowners at renewal: owned the home a decade or more, large balance, renewing on autopilot with the same lender.
- Move-up buyers within the community: selling a townhome or smaller detached, buying a larger one, needing to manage bridge timing and prepayment penalties.
- Incorporated professionals: physicians, dentists, consultants whose income sits in a corporation rather than on a T4.
- Equity-access homeowners: owners with substantial appreciation who want to refinance or open a HELOC for renovations, investment, or family support.
In plain English, what an independent mortgage agent does is read your full file, pick the lender most likely to approve at the best terms, and negotiate rate without you needing to play one bank against another. The catch: most Thornhill homeowners do not realize the alternative exists until they have already signed another renewal at the posted offer.
The agent-versus-bank decision in Thornhill
In a high-value market like Thornhill, the stakes on the rate are significant. The Financial Consumer Agency of Canada advises talking to several lenders, because different lenders may have different interest rates and conditions for similar products. As an illustration only, here is what a rate difference means in first-year interest on a $1,200,000 Thornhill mortgage; the amount is less in later years as the balance is paid down:
- 0.20% delta: roughly $2,400 of first-year interest.
- 0.40% delta: roughly $4,800 first-year.
- 0.60% delta: roughly $7,200 first-year.
That is not a rounding error. On a Thornhill-sized balance it is a renovation budget, a year of tuition, or a meaningful RRSP contribution. A bank specialist can offer one institution's products. An agent shops the same file across the full panel at once, and has no incentive to steer you toward any particular product.
What 50-plus lenders means for your file
The Canadian residential mortgage market has four broad lender tiers, each with its own sweet spot.
| Tier | Examples | Best fit for Thornhill files | Typical rate position (May 2026) |
|---|---|---|---|
| Big-Five banks | RBC, TD, Scotiabank, BMO, CIBC | Prime files, clean T4 income, simple renewals | Posted-rate-discount; often 0.20% to 0.40% above market |
| Credit unions | Meridian, DUCA, Alterna | Community-focused borrowers, flexible on equity access | Competitive with banks; slower service |
| Monoline lenders | MCAP, First National, CMLS, Equitable Bank | Best rates on prime files; strong on incorporated-professional files | Often 0.20% to 0.40% below Big-Five |
| Alternative ("B") lenders | Home Trust, Equitable Bank (B side), Haventree | Self-employed files with complex income, recovering credit | 1.5% to 3% above prime files |
Tier positioning is illustrative, not personalized. Actual rate access depends on your file's underwriting strength, insurance status, and loan-to-value.
Per FSRA, a Mortgage Agent Level 1, Jenny's licence class, may deal with financial institutions and lenders approved under the National Housing Act. Some alternative lenders fall within that permitted scope; private mortgages must be handled by a Mortgage Agent Level 2 or Mortgage Broker.
Common Thornhill scenarios
The long-term homeowner at renewal
Owned the Thornhill home a decade or more, renewed with the same lender every term. Lenders price their best rates for new clients and count on existing clients to renew on the posted offer without shopping. You can switch lenders at maturity with no penalty, because the mortgage has matured rather than been broken. The 120-day window before maturity is when you should be reviewing options, not the week the offer arrives.
The move-up buyer within Thornhill
Selling a townhome or smaller detached and buying a larger one within the community. These transactions require careful advice on portability, bridge financing, and the interaction between your current mortgage's prepayment terms and the new purchase. Getting the penalty math wrong on a large Thornhill balance can cost tens of thousands. See our Ontario bridge financing playbook and the mortgage renewal penalties breakdown.
The incorporated professional
Physicians, dentists, consultants, and small business owners whose income sits inside a corporation. Stated income on personal tax returns often understates real cash flow after corporate deductions. Certain monoline and alternative lenders run business-for-self programs that use a broader view of income. The detail is in our self-employed mortgage path in Canada.
The equity-access homeowner
Owns a Thornhill home that has appreciated substantially and wants to access equity for a renovation, an investment property, or to help a family member buy. Per FCAC, HELOCs are capped at 65% of home value and combined home-equity borrowing at 80%. Whether a refinance or a HELOC is the better route depends on your existing rate and how you plan to use the funds, which we walk through in our refinancing your home in Ontario guide.
The newcomer family
Drawn to Thornhill for the schools and established community infrastructure, often with strong income but limited Canadian credit history. Several banks and monolines run specific newcomer programs; most branches default to "thin file" pricing instead. The right routing can save 0.30% to 0.80% on rate.
"Thornhill clients often come to me at renewal having stayed with the same lender for ten years. The renewal offer on the table is almost never their best option. Five minutes of conversation and a market comparison usually changes what they pay for the next five years, and on a Thornhill-sized balance that is real money."
Jenny Tate, Mortgage Agent Level 1, FSRA #M22002086
The renewal angle: why Thornhill homeowners overpay most
If you take no action, your mortgage may renew automatically, and the Financial Consumer Agency of Canada notes that this means you may not get the best interest rate and conditions. A renewal letter shows one offer from your current lender, and you may qualify for a discounted rate lower than the one it quotes.
The mechanics most Thornhill homeowners do not know:
- You can switch lenders at maturity without paying any penalty, because the mortgage has matured, not been broken.
- Per OSFI, a straight switch at renewal does not trigger the federal stress test as long as you do not increase the balance or amortization.
- The standard rate-hold window is 120 days before maturity. Lock the rate, then negotiate.
Second mortgage and private mortgage in Thornhill
Thornhill's substantial home equity creates a different set of financing options than most GTA markets. A Thornhill detached purchased at $900,000 in 2018 is now worth $1.4M to $1.8M in most pockets. That appreciation creates equity that can be accessed without touching the existing first mortgage.
Second mortgage in Thornhill
A second mortgage sits behind the first mortgage on title. You access equity without breaking or refinancing the first, which avoids the IRD prepayment penalty if you are mid-term. In 2026, institutional second mortgages (Home Trust, Equitable Bank) typically price at 7% to 12% for 1-to-2-year terms. Private second mortgages (private lender, broker-arranged) range from 10% to 15%. The structure is almost always a short term (12-24 months) designed to bridge a specific need, renovation completion, debt payoff, investment down payment, family support, before the homeowner refinances into a clean first mortgage at maturity. See the full second mortgage guide for Toronto and the GTA.
Private mortgage in Thornhill
When conventional and institutional lenders decline because of bruised credit, a consumer proposal, self-employed income documentation issues, or a property condition, a private lender can step in. Private lenders are mostly MICs (Mortgage Investment Corporations) or individual investors who assess the deal primarily on equity and exit strategy rather than income and credit score. In Thornhill, where the equity position is often strong, private mortgages are routinely arranged at 65% to 75% LTV for 12-month terms at 10% to 14%, with a defined exit into prime or institutional financing after credit repair or income documentation is restored. See our full private mortgage guide for Toronto and surrounding GTA.
Institutional second-mortgage options may be handled within a Mortgage Agent Level 1's permitted scope. A private first or second mortgage must be handled by a Mortgage Agent Level 2 or Mortgage Broker. If your situation requires alternative financing, start with an educational conversation about the structures and licence requirements before any private-mortgage assessment.
How the process works, and what to do next
Working with a Thornhill mortgage agent runs through six steps: a free 15-minute discovery call, document collection, pre-approval or a 120-day rate hold, lender matching across the full panel, the approval and commitment letter, and the lawyer and funding stage. Total timeline is typically two to four weeks, and renewals can complete faster because there is no appraisal coordination.
Jenny Tate is a licensed Mortgage Agent Level 1 (FSRA #M22002086) operating under Tango Financial Mortgage (ON) Corporation (FSRA #13691). She holds an MBA in Finance and a Lean Six Sigma Black Belt, and has earned 50+ five-star Google reviews across Thornhill, Vaughan, Markham, Toronto, and the broader GTA. Her practice covers purchases, renewals, refinancing, home-equity access, and investment-property financing.
Whether you are renewing a long-held Thornhill detached, moving up within the community, or accessing equity from an appreciated home, the first step is a free 15-minute discovery call with a Toronto mortgage agent serving Thornhill and the GTA. Book directly at calendly.com/jtmortgages/discovery-call-1 or call (647) 642-7249.
Frequently Asked Questions

How do I find a mortgage agent in Thornhill?expand_more
Most Thornhill homebuyers find their mortgage agent through a referral from their realtor, accountant, or someone who recently went through the process. Look for a licensed FSRA Mortgage Agent (FSRA #M22002086 in Jenny Tate's case) operating under a registered brokerage. A free 15-minute discovery call lets you assess fit before committing.
Is using a mortgage agent in Thornhill free?expand_more
Yes, for standard residential transactions. The funding lender pays the agent a finder's fee on closing, so the borrower pays nothing for advice, application work, or rate shopping. Private lender deals may carry a fee that is always disclosed in writing in advance under FSRA standards of practice.
What is the difference between a mortgage broker and a mortgage agent in Thornhill?expand_more
In Ontario, both are licensed by FSRA, but their permitted lender scope differs. A Mortgage Agent Level 1 may deal with financial institutions and lenders approved under the National Housing Act. Private mortgages must be handled by a Mortgage Agent Level 2 or Mortgage Broker. Local market knowledge and responsiveness still matter within the professional's permitted scope.
What are current mortgage rates in Thornhill in 2026?expand_more
In May 2026: insured 5-year fixed (under $1.5M with less than 20% down) in the high 4% range at monoline lenders; uninsured 5-year fixed (20% or more down, or $1.5M and over, common in Thornhill) in the low to mid 5% range; variable uninsured around 3.85% to 4.05% (prime minus 0.40% to 0.60%). Purchases at $1.5M or more, or with 20% or more down, are generally uninsured, which puts you in the higher rate tier. You may qualify for a rate lower than the one quoted in a renewal letter, so compare written offers.
Can I get a second mortgage on my Thornhill home?expand_more
Yes. Thornhill homes have often appreciated substantially since purchase, making second mortgages a practical equity-access tool. A second mortgage sits behind your first mortgage on title and lets you access equity without breaking the first (and triggering the IRD penalty). Institutional second mortgages typically price at 7% to 12% for 12-to-24-month terms; private second mortgages at 10% to 15%. These are short-term bridges designed to solve a specific need before you refinance back into a clean first mortgage structure.
Do I need to live in Thornhill to work with a Thornhill mortgage agent?expand_more
No. Most mortgage agent work in 2026 is fully remote (phone, email, video call, and a secure document portal). You can live anywhere in the GTA and still work with a Thornhill agent. The location matters more for local market expertise than for physical meetings.
How many lenders does a mortgage agent typically work with?expand_more
Mortgage agents may have access to major banks, credit unions, monoline lenders, and eligible alternative lenders. A Mortgage Agent Level 1 may deal only with financial institutions and lenders approved under the National Housing Act; private mortgages must be handled by a Mortgage Agent Level 2 or Mortgage Broker.
How long does the mortgage process take in Thornhill?expand_more
Typical conditional approval lands within 2-5 business days of full document submission. Final approval comes once the appraisal and title work are complete, usually 7-14 days for a purchase. Refinances and renewals can move faster because there is no appraisal coordination.
What documents do I need for a mortgage application in Thornhill?expand_more
Standard list: 2 most recent pay stubs, 2 years of T4s or T1 General returns (for self-employed), employment letter, 90 days of bank statements showing the down payment, photo ID, and the purchase agreement if applicable. Self-employed adds business financials and CRA Statements of Account.
Can I get a mortgage with bad credit in Thornhill?expand_more
Yes, through alternative or private lenders that focus on equity, recent income stability, and exit strategy rather than historical credit. Rates run roughly 1.50%-3.00% above prime-lender rates. The structure is usually a 1-year term designed to repair credit and refinance into a prime lender at maturity.
Ready to get the best mortgage for your Thornhill property?
Book a free 15-minute call with Jenny. Whether you're buying, renewing, or refinancing, she'll review your situation and tell you exactly what your options are.
Jenny Tate
Mortgage Agent Level 1 · FSRA #M22002086 · MBA in Finance · Lean Six Sigma Black Belt
Jenny Tate is a licensed mortgage agent serving Thornhill, Vaughan, Toronto, North York, and the GTA. With access to 50+ lenders and an MBA in Finance, she builds mortgage strategies that serve your long-term goals -- not a bank's sales targets. Licensed with Tango Financial Mortgage (ON) Corporation (FSRA #13691).