Variable vs. Adjustable Rate Mortgage in Canada: Which One Are You Actually Holding?
 By Jenny Tate
Short answer
In Canada, both a variable rate mortgage (VRM) and an adjustable rate mortgage (ARM) are tied to their lender's prime rate. The difference is the payment. A fixed-payment VRM normally keeps your monthly payment level, subject to the contract's trigger provisions, so when prime moves, the split between interest and principal shifts and your amortization stretches or shrinks. An ARM adjusts your payment under the product terms when the rate changes, to support the agreed repayment schedule. A fixed-payment VRM can hit a trigger rate, where the payment covers interest but no principal. Above that rate, interest exceeds the payment; unpaid interest may be added to the balance if the contract allows.
★ Start here: Mortgage Renewal Ontario, the complete 2026 hub, the big-picture guide that ties the renewal articles together.
A variable interest rate does not tell you whether your payments are fixed or adjustable. This guide uses VRM for a variable-rate mortgage with fixed payments and ARM for one with adjustable payments. Lenders may use different product names, so check the payment provisions in your agreement. The examples below show how a rate change can affect each structure and which contract questions to ask.
Key takeaways
- Both can be linked to a lender's prime rate. Compare the offered rate and payment structure together.
- VRM = normally level payments with principal repayment affected by rates and trigger provisions. ARM = payments adjusted under the product terms when rates change.
- Product availability and names vary by lender. Read the agreement instead of inferring the structure from the word variable.
- In the hypothetical $500,000 example below, a 0.25 percentage-point rate increase shifts about $103 from principal to interest in the first month on a VRM, or raises an ARM payment by about $67.
- A conversion to fixed depends on your lender and product. Check eligibility, the offered rate, required term, fees and any prepayment charge before agreeing.
What most people get wrong
- "Variable and adjustable are the same thing." Variable interest may come with either payment structure. The agreement explains how rate changes affect your payment and principal repayment.
- "A fixed payment means I am protected." A level payment does not fix your interest rate. When prime climbs, less may go to principal. If the payment no longer covers interest and the contract permits unpaid interest to be added, the balance can grow.
- "I will just pick the lower rate." The rates need not be the same. Compare actual offers, including the lender's prime reference, discount or premium, payment terms and fees.
The one word hiding two mortgages
Both structures may be priced using the lender's prime rate plus or minus a contractual amount. The rate reference and timing of changes are product-specific. The important distinction here is how the agreement adjusts payments and principal repayment when the interest rate changes.
On an adjustable rate mortgage (ARM), payments adjust under the product terms when the interest rate changes. A higher rate generally means a higher payment; a lower rate generally means a lower payment. The payment adjustment is intended to support the agreed repayment schedule. Ask when the adjustment takes effect and how the lender calculates the new payment.
On a variable rate mortgage with fixed payments (VRM), the payment normally stays level until a contractual adjustment applies. If rates rise, more of the payment goes to interest and less to principal; if rates fall, more can go to principal. The projected payoff period may change even when the payment does not. Compare that projection with your agreed amortization, and ask how renewal or voluntary changes affect it. The separate 30-year amortization guide covers another amortization question.
For either structure, read the interest and principal amounts as well as the payment. A payment amount alone does not show whether you are repaying the balance on the schedule you expected.1
| Feature | Variable (VRM), fixed payment | Adjustable (ARM), moving payment |
|---|---|---|
| What moves when prime moves | The interest/principal split | Your actual monthly payment |
| Your monthly payment | Usually level; trigger provisions may require a change | Rises or falls with prime |
| Your amortization | Projected payoff can lengthen when rates rise | Payment adjustment supports the agreed schedule |
| Trigger rate risk | Check fixed-payment trigger provisions | Payment adjusts; check product terms |
| Easiest to budget | Level payment helps budgeting; repayment still needs monitoring | Budget must accommodate payment adjustments |
Which one are you actually holding right now?
Start with the product name and payment provisions in your mortgage agreement. A statement can provide clues, but a payment change alone does not prove which structure you hold: a fixed-payment variable contract can also require a higher payment at a trigger point.
Three ways to find out, fastest first.
- Compare statements around a lender prime-rate change. A payment that moves with the rate suggests adjustable payments. A level payment with a changed interest/principal split suggests fixed payments. Confirm the structure in your agreement because trigger provisions or voluntary adjustments can also change a VRM payment.
- Read your mortgage commitment. The document names it. Look for "adjustable" versus "variable rate, fixed payment." The phrase "fixed payment" next to "variable" is the tell.
- Ask your lender to confirm the structure in writing: "Are my payments fixed or adjustable, and when can the contract require a payment increase or lump sum? What are my trigger rate and trigger-point provisions, if applicable?"
Compare the remaining amortization and principal paid on your latest statement with the schedule you expected. If they differ, ask your lender why and what payment or lump-sum options are available under your contract.
Run YOUR numbers
See what your payment looks like across different rates and amortizations before you decide which structure fits.
Open the mortgage payment calculatorWhat prime actually does to each, in real dollars

Hypothetical worked example, not a current rate or quote: compare a $500,000 balance with 25 years (300 months) remaining, monthly payments, and a nominal annual mortgage rate of 3.60%, compounded semi-annually. Assume the mortgage rate rises immediately to 3.85% before the next payment, with no fees, prepayments or trigger adjustment. The starting payment is $2,522.81.
The table compares the next monthly payment at the same starting balance. For the ARM, the payment is recalculated over the same 300-month horizon. For the VRM, it stays at $2,522.81 for this illustration.
| After a 0.25% prime increase | Variable (VRM), fixed payment | Adjustable (ARM), moving payment |
|---|---|---|
| Your monthly payment | Stays ≈$2,523 | Rises to ≈$2,590 (+$67/mo) |
| Extra interest per month | ≈$103 shifts from principal to interest in the first month | Covered by the higher payment |
| Effect on your balance | Falls more slowly, amortization stretches | Stays on the original schedule |
| What you feel today | Nothing | About $67 more for the next payment |
Monthly rate = (1 + annual rate / 2)^(1/6) − 1. Payment = balance × monthly rate / [1 − (1 + monthly rate)^(-300)]. Actual lender calculations and adjustment timing may differ. This is a next-payment comparison, not a forecast of total term cost.
The extra interest and payment increase differ because they answer different questions.4 In this example the VRM pays about $103 less principal in the next month than it would at the starting rate. The ARM pays about $67 more and follows the recalculated repayment schedule. Later balances and interest amounts depend on subsequent rates and payments.
The trigger rate and your contract
A trigger provision changes what a level payment means. Read the threshold and the required response together.
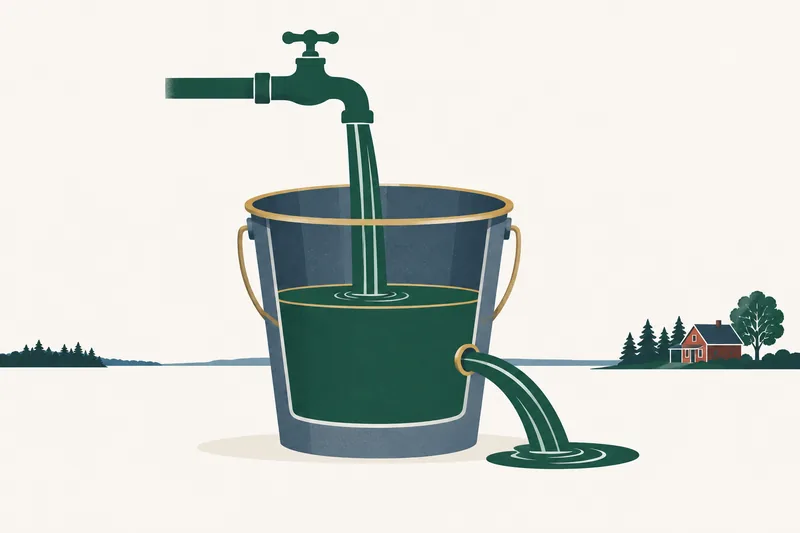
A fixed-payment variable mortgage can have a trigger rate: the rate at which the scheduled payment covers interest but no principal. Above it, the payment may not cover all interest. If unpaid interest is added to the balance, that is negative amortization. This is not an automatic outcome for every lender: the contract may require higher payments or other action. A trigger point can be a separate balance threshold requiring a response. Ask for both provisions and the available remedies.2
On the hypothetical $500,000 balance above, the interest-only threshold is approximately 6.13% under the stated semi-annual compounding assumption and $2,522.81 monthly payment. This holds the balance constant to illustrate the calculation; your actual trigger rate depends on your lender's method, balance, payment and contract. It is not a prediction of future prime rates.
If your statement shows less principal being repaid or a longer projected amortization, ask the lender to explain the change. Request the balance, remaining amortization, trigger provisions and available payment or lump-sum options in writing. A projection is not permission to keep the same payment indefinitely; the agreement and lender requirements govern.
A level payment can help with budgeting, but it does not fix the interest rate or guarantee the repayment schedule. Monitor the principal paid, remaining amortization and any notices about trigger provisions together.
Check three numbers together: your payment, the principal repaid and the remaining amortization. If they do not match your expectations, ask the lender to explain the payment provisions before choosing a new structure.
Statement-reading checklist
Who should pick which
The choice depends on your budget, repayment priorities and actual product terms. Neither structure removes variable-rate risk. Compare how each offer would handle a rate increase and what options you would have if the resulting payment or repayment path no longer fit.
The disciplined budgeter
If a level payment helps with budgeting, check how a fixed-payment VRM affects principal repayment when rates rise. Ask what trigger provisions require and whether you could afford the permitted payment increase or lump sum. A predictable payment does not guarantee a predictable payoff date.
The amortization-keeper
If maintaining the agreed repayment schedule is your priority, examine how the adjustable-payment offer recalculates payments. Test whether your budget could absorb a higher payment and ask when changes take effect. Keep checking statements and lender notices rather than treating the structure as a guarantee.
The borrower comparing a renewal
If your renewal offer has a different rate or payment, compare both structures using the same balance, amortization and payment frequency. Check how each contract would respond to a further rate increase. If your wider question is fixed versus variable, use the separate variable vs. fixed rate mortgage in Canada for 2026 guide.
The tight-cushion file
If higher payments or a required lump sum would strain your budget, compare a fixed-rate offer as well. A signed fixed rate provides rate certainty for its term, but its price, prepayment restrictions and renewal risk still matter. Ask which qualification rules apply to your proposed transaction; the mortgage stress test guide explains that separate question.
Breaking, switching, and converting: the exit math
Treat breaking a mortgage, converting with the same lender, and changing payment structure as different transactions. Each can have different eligibility, costs and contractual consequences.
Before breaking or switching lenders, request a dated payout statement showing the prepayment charge and any discharge, administration or other applicable costs. The charge depends on the open or closed product and its contract; a broad dollar range cannot tell you your cost. The mortgage renewal penalties guide explains the questions to ask.3
A conversion to fixed may be available under your lender's product terms, but it is not a universal penalty-free right. FCAC guidance says conversion conditions may apply and a fee is usually payable. Ask for the exact conversion rate, available terms, new maturity date, fees and prepayment provisions in writing. A conversion rate is the lender's offer; do not assume it matches an advertised new-mortgage or switching offer.
Two product examples checked October 3, 2026 show why the details matter. TD's variable-rate mortgage page permits conversion at its current mortgage rates, with a fixed term at least the lesser of three years or the remaining original term; that statement does not establish that all fees are waived. Scotia Flex Value Mortgage, 5 Year Open Term describes adjustable payments and conversion to any fixed-term product without prepayment charges, subject to conditions. That is an open-product example, not a rule for Scotia closed products or every possible fee.
Changing between fixed and adjustable payments may involve an amendment or a new mortgage rather than exercising a conversion feature. Ask which transaction the lender proposes, whether qualification is needed, and what costs apply. Renewal is a useful comparison point, but confirm the new product terms before signing.
What to do before the next rate announcement
You do not need a rate forecast to check your mortgage. Start with your agreement and latest statement, then work through these questions:
- Find out which structure you are on. Use the document and lender checks above. You cannot make a decision about a mortgage you have not identified.
- If you are on a VRM, ask your lender for your trigger rate in writing, and ask how much room is left between today's rate and that number. If the gap is small, that is the conversation to have now, not after the next move.
- Check your amortization, not just your payment. If you are on a fixed-payment variable and prime rose during your term, your payoff date may have moved. Ask what payment increase or lump sum would restore the intended schedule, and whether it fits your budget and prepayment privileges.
- Before renewal, compare fixed and variable offers on the same assumptions. Ask whether a rate hold is available, its expiry and conditions, and any costs or obligations.
Useful homework: gather your mortgage agreement, latest statement and renewal date. Note the rate, payment, remaining amortization and any trigger provisions. An unexpected amortization change is a reason to ask questions, not proof of a particular product. If you are considering an exit or conversion, add a written conversion offer or dated payout quote.
Frequently asked questions
What is the difference between a variable and an adjustable rate mortgage in Canada? expand_more
This guide uses VRM for variable interest with fixed payments and ARM for variable interest with adjustable payments. With fixed payments, a rate change normally shifts the interest and principal portions; trigger provisions may require action. With adjustable payments, the payment changes under the product terms. Lenders may use different names, so confirm the agreement.
Which is more common in Canada, a VRM or an ARM? expand_more
Both payment structures are available in Canada, and availability and product names vary by lender. Ask which structures the lender offers and confirm the payment provisions in your agreement. Do not assume that a product labelled variable has fixed payments.
How do I tell if my mortgage is a VRM or an ARM? expand_more
Read the product and payment provisions in your agreement and ask your lender to confirm them in writing. Statements around a prime-rate change can provide clues, but a payment change alone is not proof: trigger provisions or voluntary adjustments can also change a fixed-payment VRM payment.
What is a trigger rate, and does it affect adjustable rate mortgages? expand_more
For a fixed-payment variable mortgage, the trigger rate is the rate at which the payment covers interest but no principal. Above it, unpaid interest may be added to the balance if the contract allows; the lender may instead require higher payments or other action. A trigger point can be a separate balance threshold. Adjustable payments respond to rate changes rather than retaining that fixed-payment threshold. Check the actual contract.
Can I switch from a variable to an adjustable mortgage, or to fixed? expand_more
A conversion to fixed depends on your lender, product and contract. Check eligibility, the offered fixed rate, required term, fees and any prepayment charge. Changing between fixed and adjustable payments may require an amendment or a new mortgage. Ask whether qualification is needed and request the costs and new terms in writing.
Which is cheaper, a variable or an adjustable mortgage? expand_more
Do not assume the starting rates or discounts are equal. Compare actual offers on the same balance, amortization and payment frequency, including fees and prepayment terms. The eventual cost also depends on rate changes, payment adjustments and how much principal you repay.
What happens to my payment when prime rises on each type? expand_more
With adjustable payments, the lender changes the payment under the product terms to reflect the rate change. With fixed payments, more normally goes to interest and less to principal, so the balance falls more slowly. A trigger provision may require higher payments or another response. Ask when adjustments take effect.
Do adjustable rate mortgages in Canada have rate caps? expand_more
Check the specific agreement. Ask whether it includes an interest-rate cap or a payment cap, how any cap works, and what happens to principal repayment if interest exceeds the payment. Do not infer a cap or its absence from the ARM label or from a product in another country.
Which should I choose in 2026, a VRM or an ARM? expand_more
Compare how each contract responds to rate increases against your budget and repayment plan. Adjustable payments may suit a household that can absorb payment changes; fixed payments require attention to principal repayment and trigger provisions. Use actual offers and contract terms rather than relying on a forecast.
Does the prime rate affect fixed-rate mortgages too? expand_more
A fixed interest rate you have signed stays fixed for its term. Rates offered on new or renewed mortgages can change with lender funding costs, risk and market conditions; they are not determined by prime alone. A prime-rate change does not by itself change your signed fixed rate.
Ready to take the next step?
Bring your mortgage agreement and latest statement. Jenny can help you compare the payment structure and identify the lender questions needed before a conversion or renewal decision.
Check the contract before relying on a level payment: trigger provisions may require higher payments, a lump sum or another lender-approved response.
★ 60+ Google reviews, rated 5.0 · Mortgage Agent Level 1 · FSRA #M22002086 · MBA in Finance
No obligation, no sales pitch, just a second opinion on your numbers.
Jenny Tate
Mortgage Agent Level 1 · FSRA #M22002086 · MBA in Finance · Lean Six Sigma Black Belt
Jenny Tate is a licensed mortgage agent serving Toronto, Burlington, and the Greater Toronto Area. With an MBA in Finance, a Lean Six Sigma Black Belt, and access to 50+ lenders, she helps clients secure better mortgage structures. She has earned 60+ Google reviews, rated 5.0, across the GTA. Licensed with Tango Financial Mortgage (ON) Corporation (FSRA #13691).